


“Elections are won by men and women chiefly because most people vote against somebody rather than for somebody.”
— Franklin P. Adams
They didn’t want him.
The blue wave is here.
Today I’ll give you a deep-dive dissection of what just happened in the US mid-term elections.
And Australia, no doubt, will feel the effects, so I want Aussie investors to be prepared for what is to come.
It was a relief to see the ASX small-cap market get a solid bounce today.
Markets always love certainty.
I’ll get into potential impacts for the ASX on Saturday, but for now, let’s unpack the seismic events in the US political system.
Democrats have taken control of both houses of Congress with a blue shift far beyond what even the most optimistic polls predicted.
In the Senate, the Democrats flipped historic deep-red seats to take the majority.
James Talarico won the Texas Senate seat cleanly, but the shift ran far deeper across the Lone Star State.
Texas’s governorship went blue. Its attorney general. Its powerful railroad commissioner, who regulates its oil and gas fields, swung blue for the first time in two decades.
Elon Musk, who spent around US$180 million in the Texas race, faced a disappointing night in his new home state.
There’s a lot you can buy with US$474 million. About 113 million packets of Tim Tams is how much the world’s richest man spent on the election.
That’s about 1,800 Mount Everests’ worth of the biscuits stacked on top of each other. All for naught.
Humble pie or less than meets the eye
All up, a dramatic night in politics. But beyond the political spectacle, the economic changes will be modest by comparison.
As with most midterms, the vote against the ruling party moderates the magnitude of prior political swings.
Excesses will be pared, hubris will shift parties and a sense of normalcy (followed by tedium) will return to the polity.
For the market, this centrist turn is also broadly positive.
As we saw in the relief rally overnight, short positions quickly unwound as the wider fears of a broader AI capitulation moment failed to materialise.
Looking at history, it shouldn’t be a surprise. Since 1950, US stocks have consistently risen in the year after midterm elections.
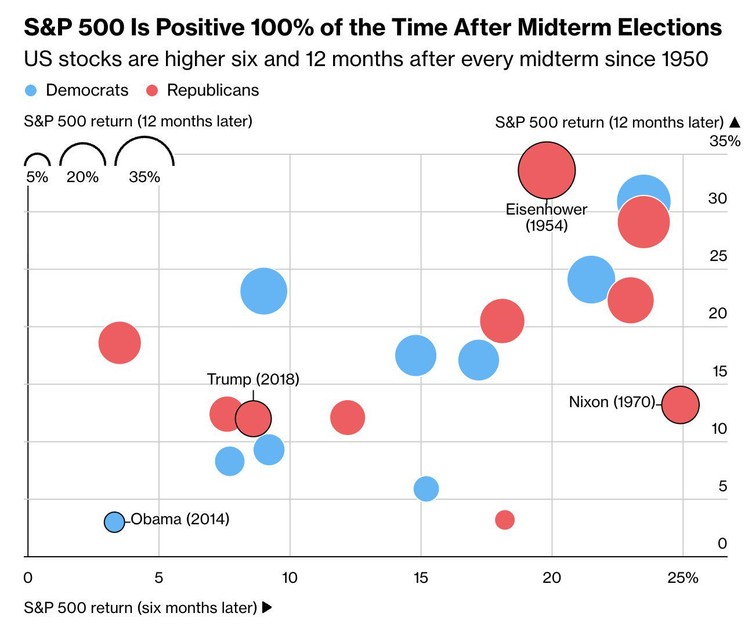
Source: Morgan Stanley
[Click to open in a new window]
We’re not in Kansas anymore
Still, it has to be said that this felt like a repudiation of all things Trump.
Throughout the campaign, Trump urged supporters to ‘pretend, please, that I’m on the ballot’. Voters have taken him at his word.
NBC’s exit poll shows how far his coalition slipped. Young voters swung violently away from Republicans. Around 61% of young said their vote was to express opposition to Trump.
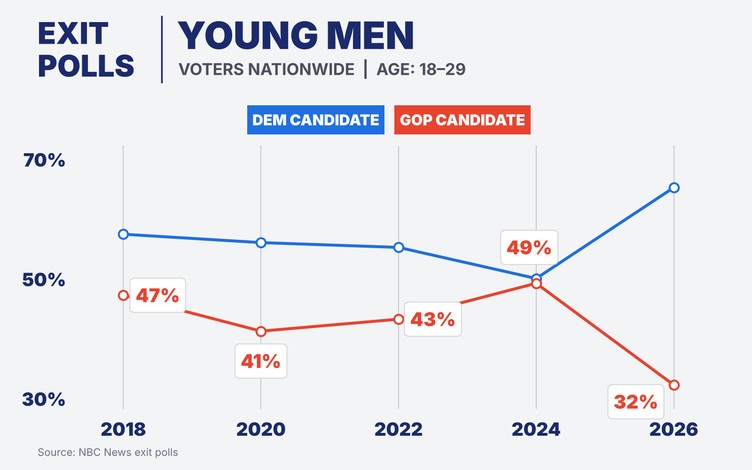
Source: NBC
[Click to open in a new window]
Meanwhile, Latino voters went Democrat 62% to 35% in House races, after giving Trump 45% of their vote in 2024.
The tepid turnout among his base helped deliver historic swings in states like Kansas, which saw the election of the first Democratic Senator since 1932.
That’s so far back that Judy Garland was filming The Wizard of Oz at the time, and the democrat in question was a segregationist.
Still, some things never change.
It’s the economy, stupid
The issue that came up again and again in exit polls was the economy.
On paper, real GDP grew at a strong annualised 3.4% in the September quarter, its fastest pace in a year.
But in nominal terms, that 5.8% growth was driven by gargantuan AI spending and contributed to the broader inflation, which squeezed the bottom half.
For the majority whose wealth is tied up in homes and retirement accounts, the pressure from the bowser has been the defining struggle.
On election day, the average price of petrol in the US hit US$4.12 a gallon. That’s the highest ever recorded on an election day in nominal terms.
Unlike presidents who must weather the storm of world events, Trump faced voters over decisions that felt like his own.
The war with Iran was a choice made in the White House. So was the trade war with Canada and others, which saw 50% tariffs placed on more than US$20 billion of Canadian goods in August.
JD Vance laid the loss squarely at the feet of the War, something even Trump conceded today.
Now, Brent crude prices are down 18% over three sessions as the market hopes for a bipartisan end to the conflict. We’ll see if this can hold.
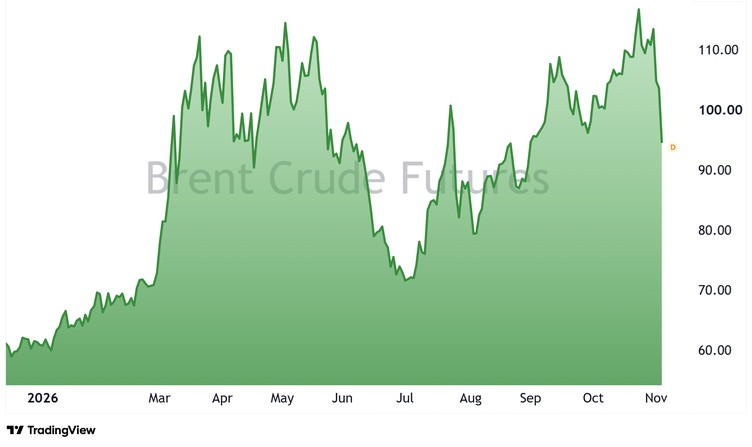
Source: TradingView
[Click to open in a new window]
Beyond Iran, there are four other major changes that we should anticipate in the coming months.
A president under the microscope
First, a White House slowed down and distracted by investigations.
With subpoena power, Democrats can now dig into the administration directly. In exit polls, nine out of ten ranked corruption alongside the cost of living as a deciding issue in the election.
So the mandate is there.
On election night, Dems made their intentions clear, with threats like ‘Lawyer Up’ from the incoming chairman of the Oversight Committee, Robert Garcia.

Source: x.com
When it comes to options, there’s plenty on offer.
First up will be Pete Hegseth, against whom articles of impeachment have already been filed by outgoing Republican Thomas Massie.
Massie broke with Trump and the GOP over Epstein, another festering boil that Democrats are keen to pick at.
But the list goes on: Trump family crypto ventures, Trump Jr.’s defence contract wins, Jared Kushner’s $2 billion Middle East slush fund.
Democrat leadership has told the rank and file to steer clear of a third attempt at impeachment of Trump, but these investigations will still consume the presidency and its allies.
Healthcare returns
Second, expect the political fight to shift back toward healthcare.
El-Sayed, a physician and Michigan’s newly appointed Senator, is likely to lead an energised left that is pushing for Medicare for All, or at least for much larger health spending.
Single payer has little chance of surviving a veto. But reinstating the funding for Medicaid and hearings on premiums, claim denials and insurer profits are far more likely.
Insurers have proposed median rises of around 15% for individual premiums next year, handing Democrats a ready-made target.
That means headline risk for US health insurers like UnitedHealth [NYSE:UNH] and CVS Health [NYSE:CVS] which are already under political pressure to dismantle their empires.
Congress comes back
Third, and perhaps most important, Congress is likely to reassert itself.
Earlier war powers resolutions on Iran failed in a Republican Senate. Now the White House will face real pressure to seek approval before escalating further.
A bill named ‘End Trump’s Tariff Tax Act’ has already been filed, which would look to roll back levies on Canada and other laws used in the trade war.
AI and data centres are next in line. Rising power bills have made data centres a bipartisan grievance.
Democrats have backed the GRID Savings Act, which would force developers to pay for the grid upgrades their projects need, but this story goes beyond Congress.
Data centres go global
Voters in 10 states decided 41 local data centre measures last night. These ranged from outright bans to votes on specific projects.
Some are still coming in, but early results are lopsided: restrictions had passed or were leading in at least 33 measures, with only one pro-development win so far in North Dakota and about a dozen still uncounted.
All of that would add costs and confusion to the AI build-out at a delicate moment.
Some may see this as the pin for hyperscalers and the AI trade. Instead, I think this is likely to be its major international pivot.
By one estimate, the US has 5,427 data centres; that’s roughly 10 times as many as any other country in the world. China, by comparison, has only 450.
These facilities were also highly concentrated in states like Northern Virginia, Texas and Ohio, the latter two states, which were part of the blue-wave backlash.
Outgoing Texas Governor Greg Abbott, for example, issued an 11th-hour halt on new environmental permits for data centres in Texas in late September.
The idea was to tamp down on anger over rapid development before opening them up again after the elections.
Now he’s out there’s an open question about what’s next for the state.
Many first-time developers had crowded into the state on the back of favourable regulations that will likely shift under them. Consolidation is likely.
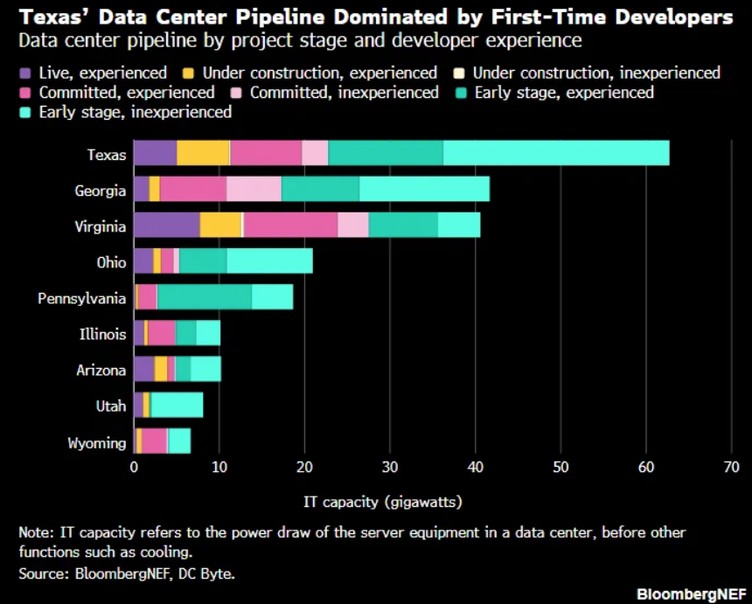
Source: Bloomberg
[Click to open in a new window]
Their loss will be the rest of the world’s gain. Many governments have made it clear that they are desperate for data centre capacity in their countries.
Even with local pushback, many will dangle tax incentives to try and pull hyperscalers to invest and build.
That’s because nations see it as a form of national security for an uncertain digital future.
I’m sure we’ll see Jensen Huang of Nvidia talking up data sovereignty in the coming months.
The high water mark
Stepping back, it feels like we’ve passed the high-water mark of the Trump era.
Republicans are already distancing themselves from the Trump brand of politics.
That will be easier for some.
JD Vance’s chances of a successful ’28 presidential run halved last night.
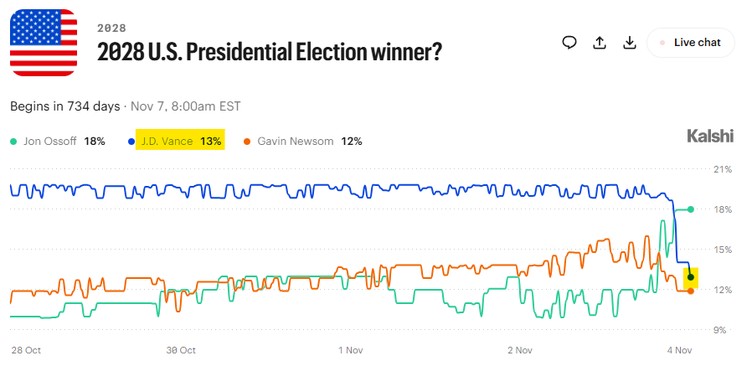
Source: Kalshi
[Click to open in a new window]
When all’s told, the Iran conflict will stand as the beginning of the end.
What was once sold as international ‘5D chess’ now looks, with hindsight, more like a running joke from Beijing.
The joke goes that whenever the US finally gets serious about the strategic, military and economic challenge posed by China, America’s ‘Old friend Middle East’ returns to pull Washington’s focus away.
From the right, the verdict is harsher still. As Christian Podcaster Joel Webbon put it earlier this year, it was ‘a generational coalition squandered for Israel.’
The blue wave may change less in law than many expect.
But for the next two years, the president will be playing defence, and markets will have to price in a US Congress that can once again say no.
This Saturday, I’ll bring you some key ASX investment themes to consider in light of the new political dynamic in the US.
‘For the times they are a-changin’
Regards,
Charlie Ormond,
ATLAS and Altucher’s Investment Network Australia


Comments